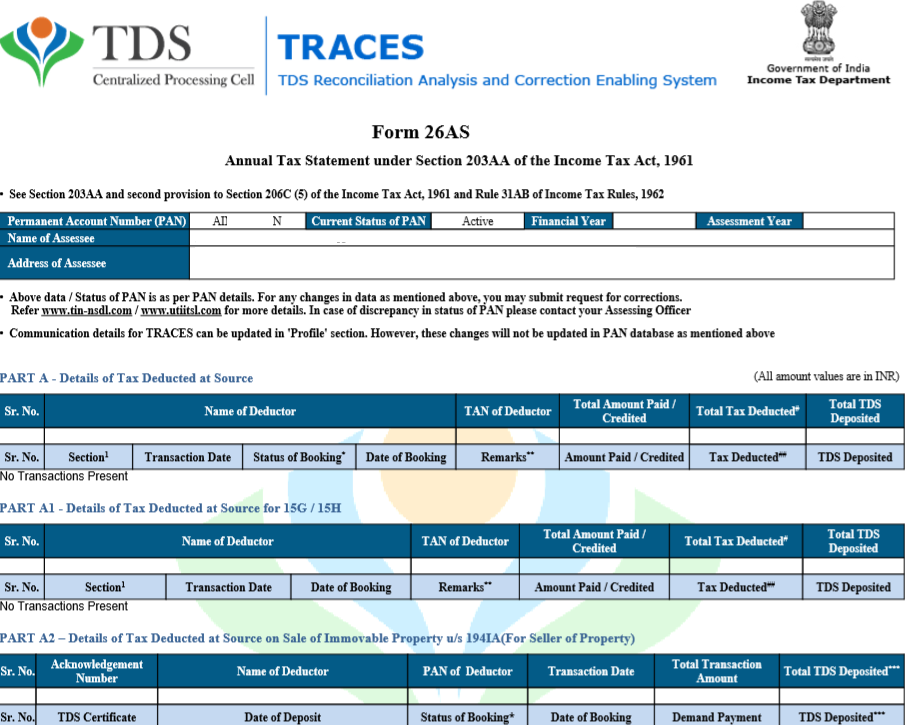
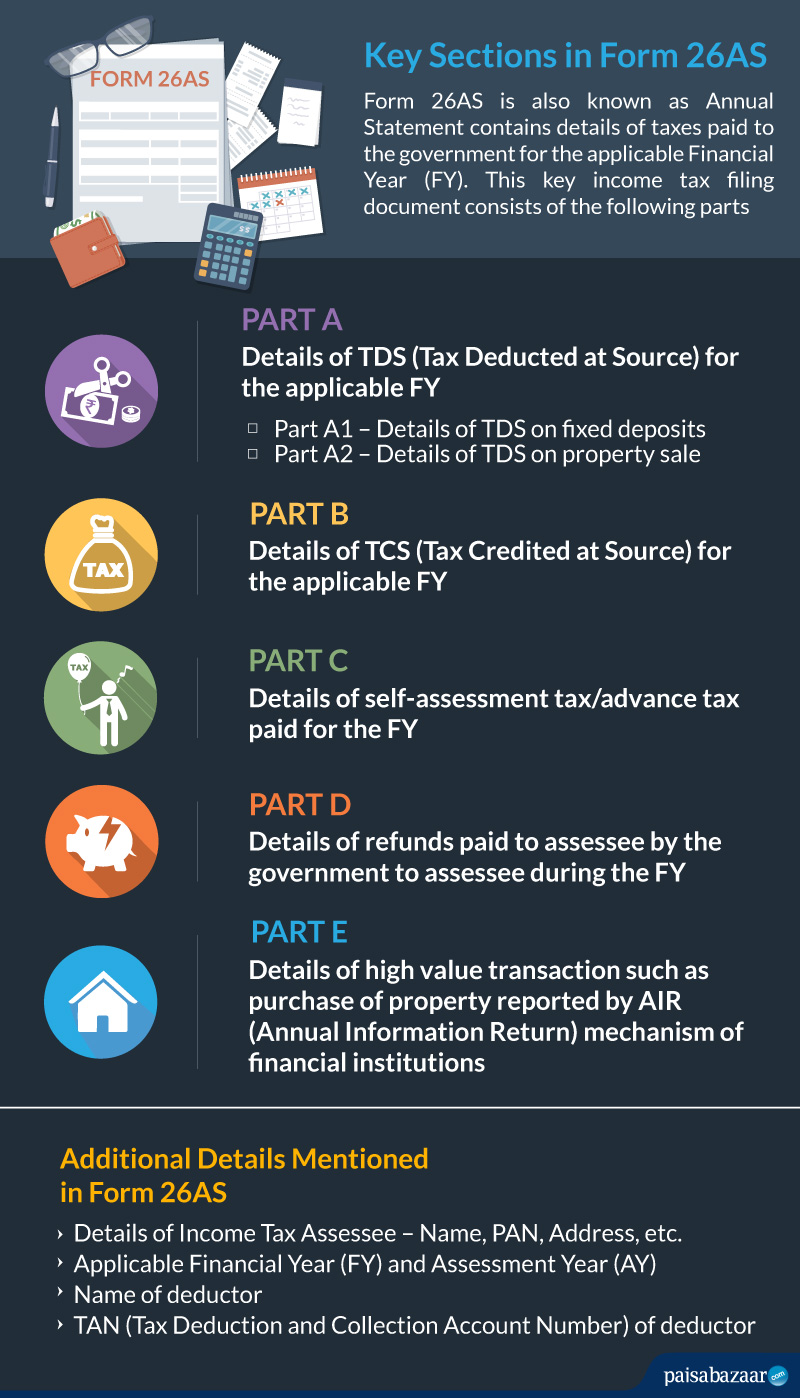
Form 26AS for each financial assessment year is divided into multiple parts. The tax credits (to government tax authorities) appearing in Part A, A1, and B of this form are given on the basis of details furnished by the deductor/collector in the TDS/TCS statement filed by them. Brief details of the sections are provided below:
Form 26AS Part A
Part A of the form contains details of the Tax Deducted at Source (TDS) in Indian currency (INR). This section of the form exclusively highlights the TDS deducted from your salary/pension income, TDS deducted by the banks on the interest generated from your investments.
Form 26AS Part A1
This section of the form is specially kept for the details of TDS from Form 15G/15H. This portion of the form shows transactions in financial institutions such as banks where the individual has submitted Form 15G/15H. TDS, in these cases, would be zero because the individual has already submitted Form 15G/ Form15H to the institution concerned, and they would not deduct any tax based on the information in this form. This section also enables you to keep a track of the earned interest that has not been taxed.
Form 26AS Part A2
This section of the form contains details of TDS credit applicable to sale of house property. Part 2 of the form would show a TDS credit on behalf of the seller of a property and can be adjusted against the total tax liability of the property seller. The rate of TDS applicable to the proceeds on sale of a property is 1% as of FY 2022-23.
Form 26AS Part B
This section of the form is kept for the details of the Tax Collected at Source (TCS). This tax is collected by the seller from the buyer at the time of sale of specified category of goods (such as liquor, parking lot, toll plaza, etc.) The amount is deposited by the collector to the government on a quarterly basis.
Part C: Form 26AS Part C discusses and maintains the details of tax paid other than TDS or TCS. If you have paid advance tax or self-assessment tax, it will be listed here. Whenever you deposit advance tax /self-assessment tax directly to the bank, it will upload this information within three days after the cheque has been cleared.
Part D: This part of the income tax Form 26AS keeps the details of paid refunds. All the refunds that you have applied for and received will be listed under this section of the annual tax statement. It may be helpful to keep a track of this information to check if you have been paid for all of the tax refunds you have applied for.
Part E: The Part E of the Form 26AS is responsible for keeping the details of the Annual Information Return (AIR) transactions. If you make some high-value transactions, such as a purchase of property, investment in mutual funds, etc., these transactions are automatically reported to the Income Tax Department by banks and other authorities through the AIR.